
 Login

Alphabet vs. Amazon vs. Microsoft: Which "Magnificent Seven" Stock Is the Better Buy Right Now?
Key Points
The ways consumers and companies use computing technologies is a big reason for the performance disparities between these tech giants.
Although the underlying dynamic will change again at some point, that shift is at least a couple of years away.
The truth is, in the long run, you'd probably be just fine with any of them. If you've only got room in your portfolio right now for one new position among "Magnificent Seven" members Alphabet (NASDAQ: GOOG)(NASDAQ: GOOGL), Amazon (NASDAQ: AMZN), and Microsoft (NASDAQ: MSFT), however, it should arguably be Google parent Alphabet. Here's why.
Why not Microsoft or Amazon?
If you already hold stakes in Amazon or Microsoft, you're hardly doomed. Microsoft remains the centerpiece of the personal and professional computing business, and Amazon is still the king of e-commerce as well as the leader in the cloud computing market.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In a valuation environment that leaves no room for error or weakness, however, those two bring company-specific concerns to the table that could turn into stumbling blocks.
Image source: Getty Images.
For Microsoft, the key concern is its waning relevancy within the workplace, or for that matter, at home. Although its productivity software titles like Word and Excel are still popular enough, Microsoft Office's dominance in the basic enterprise software arena continues to wane. It's ceding ground to Google Workspace, which is increasingly seen as less restrictive to use.
The company's also losing ground on the chat-based AI assistant front. Sure, Microsoft recently touted the fact that its Copilot app serves 30 million paying Microsoft 365 Copilot customers.
Yet take a look at the details. While this professional version of Copilot integrates nicely into the cloud-based/subscription-based version of Microsoft Office 365, the AI tool isn't necessarily being sought out by users. Rather, many of these subscribers are being added to existing Office 365 subscriptions, whether those subscribers asked for it or not (very likely at nominal additional costs). And it's still tethered to productivity software that's slowly losing market share. Meanwhile, the free-to-use consumer-facing version of Copilot only accounts for about 3% of the AI chatbot market while ChatGPT boasts a commanding share of 79%, according to data from Statcounter.
Statcounter adds that Microsoft's flagship operating system, Windows, is also losing ground. It slid to a record low market share of 63% in August thanks to soaring use of Apple's OS and even open-source Linux, both of which reached record market shares that month. In this vein, Microsoft has now reported two consecutive quarterly declines in Windows' revenue.
Connect the dots. It's not doing anything "wrong," per se. Microsoft's cloud business appears to be thriving, in fact, with revenues up 27% year over year a quarter ago, thanks to AI-driven demand. The company's just running into headwinds on too many other fronts -- even its video gaming arm, which suffered a 10% slump in revenue for the quarter ending in June.
As for Amazon, the worry is simpler and far more straightforward. It's planning on spending an enormous sum on capital investments this year -- mostly on AI infrastructure -- with no assurance that this capex will curb the deterioration in its share of the cloud computing market. Though it's on pace to shell out $220 billion on capital expenditures in fiscal 2026, numbers from Synergy Research Group indicate Amazon Web Services' market share has continued shrinking from 2020's peak of 34% to 28% as of Q2 of this year. Microsoft Azure has also been sliding, by the way. Meanwhile, third-place Google Cloud has been gaining share.
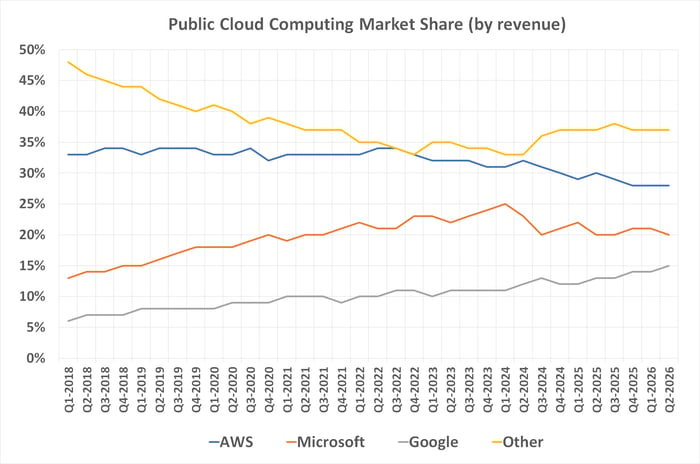
Data source: Synergy Research Group. Chart by author.
Sure, there's more to both companies than their cloud businesses. But it's difficult to deny that every technology company is prioritizing the cloud opportunities being driven by AI's growth. These two names aren't knocking it out of the park on this front.
Why Alphabet
Google parent Alphabet is knocking it out of the park on the cloud computing front, of course, reporting 82% year-over-year revenue growth for this arm during the second quarter. Whatever it's doing (particularly as it pertains to AI) is clearly working.
Moreover, unlike Microsoft and Amazon, everything else Alphabet is doing is also working well.
Take its search business as an example. Google's advertising revenue -- including YouTube -- grew by more than 14% during the second quarter, with search-based advertising revenue specifically improving 15%. Subscription-based revenue and device revenue (Google makes its own smartphones and owns the Android mobile operating system, which funnels people to the Play Store) grew by more than 15% year over year.
The company is demonstrating strength in ways that don't appear directly on its income statement, too. Statcounter's numbers suggest that Android is at least maintaining its leading share of 67% of the worldwide mobile operating system market. And within the United States, TV ratings agency Nielsen reports YouTube is the most-watched streaming platform in terms of total viewing time, and is growing its share largely at the expense of venerable Netflix.
This leadership doesn't directly generate revenue. It does, however, confirm that Alphabet is doing the things that generate revenue, and doing them well.
Now, and for a while
This won't always be the case, of course. There was a time when Microsoft could do nothing wrong. Ditto for Amazon. Those times may come again for those two, just as a time may come when macro conditions don't favor Alphabet's strengths as much.
The environment right now and for the foreseeable future, however, is one that favors Google's parent far more than it does the iconic software and e-commerce giants.
The personal computing space has been democratized, for instance, not just by more hardware choices (mobile devices are now viable alternatives to traditional desktops and laptops), but also by the wider adoption of options other than Windows or Microsoft's productivity software. Amazon's early lack of in-house technological development capabilities, meanwhile, is still a key reason its cloud business is losing share to Alphabet.
Alphabet, conversely, entered this era of connected computing ideally positioned. Not only is Google Search a perfect jumping-off point for Alphabet's AI-powered chat assistant, Gemini, but the demand for more mobile computing has turned Android into a critical platform. Recently rising streaming subscription prices have also made YouTube more attractive as a free-to-use alternative.
This backdrop and these conditions will eventually change. They aren't apt to change for a while, though, which means they should provide sustained tailwinds for Alphabet. Yes, the stock has essentially drifted since May, but this dynamic is much bigger than a few tepid months.
Should you buy stock in Alphabet right now?
Before you buy stock in Alphabet, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Alphabet wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $375,240!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,403,292!*
Now, it’s worth noting Stock Advisor’s total average return is 933% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
*Stock Advisor returns as of October 1, 2026.
James Brumley has positions in Alphabet. The Motley Fool has positions in and recommends Alphabet, Amazon, Microsoft, and Netflix. The Motley Fool has a disclosure policy.

